Central banks don’t just set interest rates out of thin air. They manipulate the actual flow of cash in the economy through open-market operations. These are the daily purchases and sales of government securities by the central banking authority. The goal is simple: regulate the money supply and credit conditions continuously. Sometimes, they buy. Sometimes, they sell.
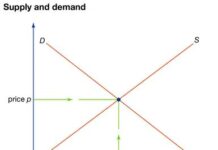
The mechanism is straightforward but powerful. When a central bank buys securities on the open market, it injects money into the system. This has three immediate effects. First, it increases the reserves of commercial banks. More reserves mean banks can expand their loans and investments. Second, the increased demand for securities raises their price. Since bond prices and interest rates move in opposite directions, this effectively reduces the interest rate on those specific government securities. Third, and most broadly, it pushes down general interest rates. Lower borrowing costs encourage business investment.
“When the central bank purchases securities on the open market, the effects will be to increase the reserves of commercial banks, a basis on which they can expand their loans and investments.”
The reverse happens when the central bank sells securities. It pulls money out of the banking system. Reserves shrink. Banks have less capacity to lend. Interest rates rise. Business investment slows. This is the primary tool for tightening credit conditions.
However, this tool isn’t without controversy. In the United States, these operations customarily involve short-term government securities, particularly Treasury bills. Why short-term? Supporters of this narrow focus argue that dealing in both short-term and long-term securities distorts the interest-rate structure. They believe this distortion leads to an inefficient allocation of credit. The market should determine long-term rates based on long-term expectations, not central bank intervention.
Opponents disagree. They argue that intervening in the long-term market is entirely appropriate. Long-term interest rates have a direct influence on long-run investment activity. This activity, in turn, drives fluctuations in employment and income. If the central bank wants to stabilize these broader economic indicators, it may need to influence long-term rates directly.
There is also a secondary aim here: stabilizing the prices of government securities. This aim can conflict with the central bank’s primary credit policies. Sometimes, the market needs stability in the debt market more than it needs a specific credit stance. When these goals clash, the central bank has to make a choice.
Observers remain divided on the advisability of these policies. The debate isn’t just about math. It’s about philosophy. Do you trust the market to set long-term rates? Or do you believe the central bank must actively shape the investment landscape to protect employment and income? The answer determines whether open market operations focus strictly on short-term liquidity or extend into the longer-term bond market. The choice shapes how money flows through the economy, for better or worse.