It’s late spring now. This means organizing boxes. Find the check you forgot. This is free money that you can use for your grocery budget or unexpected bills. You might be tempted to grab your phone, take a picture and call it a day.
But wait.
This simple operation has strict technical rules. If you are not careful, your mobile deposit will be rejected. This happens often. Unclear picture. Incomplete numbers. It’s a bad angle. Suddenly you find yourself in limbo. You lose days. You lose your patience.
Understanding why banks reject these documents is more than just compliance. This protects the cash flow. One wrong move and your deposit can be permanently frozen. Let’s look at the specific standards that lead to the trip up the banking systems.
Why mobile checking accounts fail due to High Rates
We rely on applications to manage our liquid assets. It is efficient. Skip the branches. You can skip the line. The data shows that this change is accelerating. Mobile deposit usage is expected to grow by 40% in 2024 alone. That’s a big adoption curve.
But there is no point in rushing.
When you’re in a hurry, you sacrifice image quality. Think of this as over-aggressive pruning of shrubs. It cuts off future growth. From the point of view of banks, careless scanning can cause the transaction to fail. Financial institutions report that 15% of rejections are directly due to poor image quality.
Why is this happening? Users photograph checks in dark rooms. They shoot from odd angles. Click Submit before checking for clarity. The system will reject it immediately.
This is a trap that most people fall into. When you press the button, the clock starts. This is not true. The standard five-day regulatory deposit period only starts when your bank has officially accepted your digital file. If they say no on the first day, your money is not “on its way”. It’s just back in your hands and the clock hasn’t started yet.
Photographic Details That Render Checks Unacceptable
The algorithm behind mobile deposits is ruthless. They don’t care if you are a loyal customer or not. They care about data integrity.
What if there is a shadow? Rejected. What should I do if the characters are unclear? Rejected.
The rules are simple. It’s the perfect frame. Also, all four corners must be visible. Clipping the edges amputate the transaction. The system cannot verify the format. You lose the ability to certify authenticity.
Certain data points must be clearly recorded.
- Serial number.
- numeric amount.
- Release date.
- signature.
Just a glare hiding the signatureature is enough to deny. These failures resulted in “treasury penalty”. This means that the funds are delayed. Instead of getting your money within 1-2 days, you have to wait another 5-7 business days.
People often make mistakes. forget the back.
You have to photograph the reverse side as well. The endorsement matters. If the back of the check is not photographed or cannot be read, the system holds the deposit. It is a hard stop. There are no exceptions.
How banks look at incomplete digital data
It’s not just about the photos. It depends on the information you enter.
Security filters scan all information related to electronic slip. If you enter an incorrect IBAN number, the transfer will be interrupted. If the bank’s system detects a discrepancy, the process stops.
Another important reason is the lack of text. Some checks require the amount to be written on the front of the check. If it is lost or illegible, the bank marks the document with “enhanced monitoring”. They will send an urgent request for additional information. Your money is locked until you provide proof.
This creates a bottleneck. You spend hours sending documents by email. It’s a waste of time. Liquidity has been lost.
There is a lot of myth associated with post-dated checks. People think they should wait until the check is dated before scanning it. Don’t do this. Most banks now accept post-dated checks through a digital interface. Paper doesn’t have to sit in your drawer for weeks.
Banks don’t want dates to be a problem. They want transparency. They want to make sure the pictures aren’t fake. If you scan correctly, you will get your money faster. If you rush things, you pay the price of impatience with time and pressure.
Trade-Off of Convenience
Mobile deposits save energy. You saved the trip. Save time in line. However, with this convenience comes high accuracy standards.
The alternative is clear. You can be fast, or you can be successful. if you are sloppy, you rarely get both.
A 15% failure rate is not an average of small errors. This was a warning shot. You can see that the system is monitoring you. It shows that your efforts are only worthwhile if they meet the standards.
If you skip the verification step, you’re gambling your cash flow. Assuming the image is good enough. The bank assumes We are not. they are usually right.
If you find a forgotten check this spring, take a deep breath. Light the room. Frame the corners. Confirm your signatureature. Scan the back side. Check your IBAN number.
It takes ten seconds longer. It saves ten days of waiting.
Is it worth the rush? Probably not. But we do it anyway. This is because we believe it is faster than the algorithm. We are not.
Hidden costs of rejected deposits
Most people think that cashing a check has something to do with the bank. This is not true. It’s all about algorithms.
You’re not talking to a banker. You enter your information into the machine and it determines in milliseconds whether you are human or a fraud. Even if the machine says no, your money won’t just wait. It stalls. “rejection rate” is not abnormal. This is a bottleneck.
The user interface of some applications now includes tutorial videos. they are good. Pay attention. This is a small investment and can protect you from losing liquidity over several days. But knowing and doing are not the same thing. You need a routine.
Think of it this way. Without user instructions, the system is blind. Your job is to send a clear signal.
Here’s how to stop rejection.
The lighting trap
The shadow is your enemy.
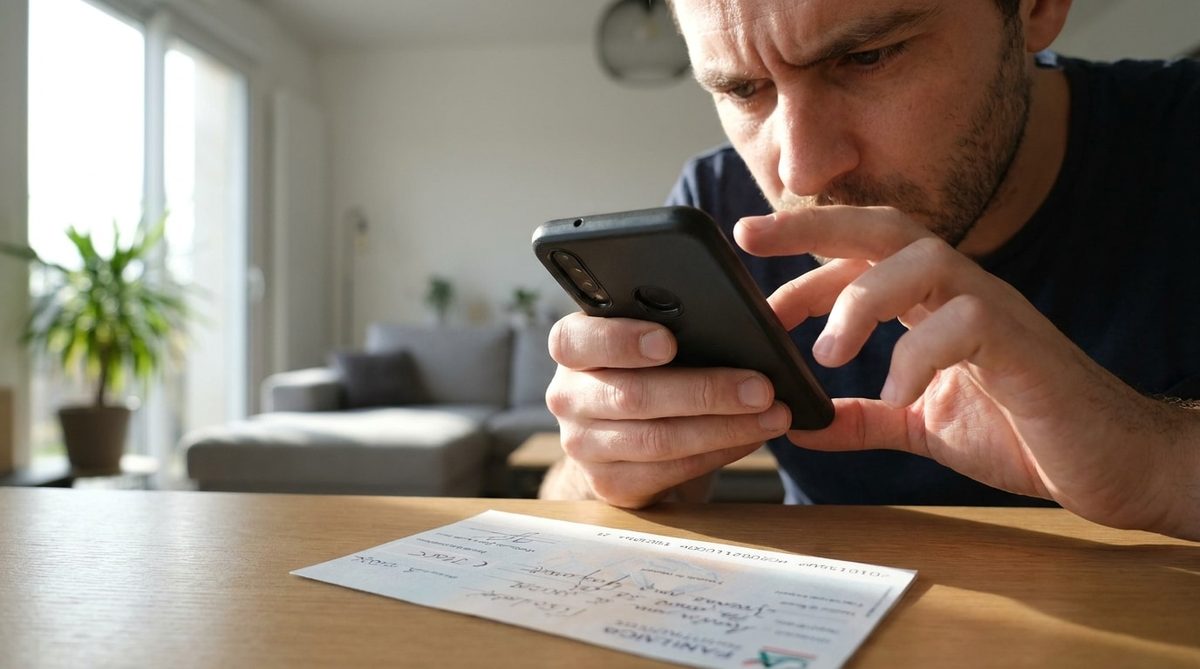
When you place a check on a table, a shadow will be created. The mobile phone casts a shadow. The check casts a shadow. Algorithms hate shadows. It confuses them for damage, altered and low quality images.
Fix: Go to window. Natural light is non-negotiable. Lay the check flat. Stand back. Make sure the light hits the surface evenly. There are no dark corners. There is no strong contrast.
Error: You are holding your phone too close. You turn off the light. Create an outline for the check. The software sees a blob. It rejects the image.
Frames are more important than you think
No professional camera required. You need a steady hand and a clean background.
Most checks have microprints, security designs and special margins. The app uses these to verify authenticity. If you cut off the ends, the confirmation will fail.
Solution: Use a dark surface. Dark table and white paper contrast. Helps focus the camera. Center the check. Make sure all four corners are visible. Keep the phone parallel to the check.
Error: Tilt your phone. Tilting the image distorts the numbers. Or worse, cropping too tight. If the check number is cut, the deposit is dead. Systems cannot read what they cannot see.
The ignored back side
This is where most people fail.
They deposit the front. They wait. They get rejected. Why? Because the algorithm needs to scan the back side.
Solution: Sign the back. Clearly state your full ID number or account number. Some banks have such requirements for large amounts. Please scan. Images must be readable. There are no stains. No unclear signatures.
Error: Back scan skipped. The algorithm expects it. If you skip it, you skip security. You have been marked as incomplete. Or it is marked as suspicious. In either case, your money will be withheld.
Why this routine saves you time
You might find it annoying to spend an extra 10 seconds.
it is not. It’s efficient.
Every rejection means a trip to the bank every time I was rejected. It means waiting. This means you are explaining yourself to someone who is tired of your problem. This means that your budget will be interrupted. Cash flow is king. Breaking it will cost you extra time and stress.
The smooth deposit process is invisible. You won’t notice it until it breaks.